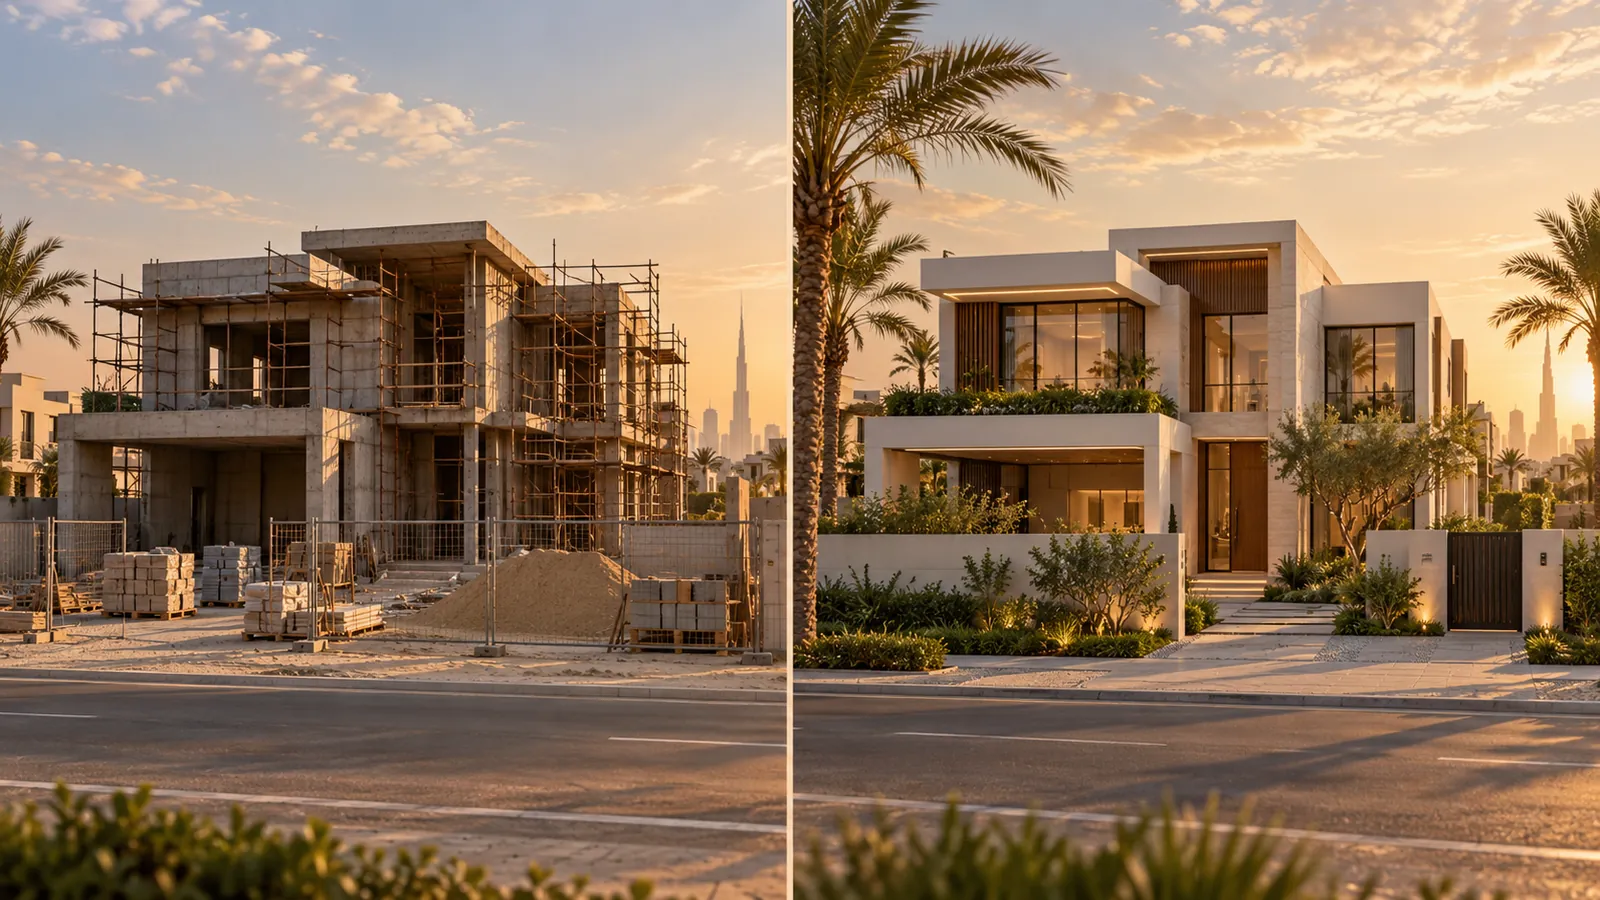
Key takeaways
- Off-plan is bought from the developer before completion; ready is a finished home, usually bought from its current owner.
- Off-plan sales are registered in DLD’s interim register (Oqood); a ready purchase ends with a title deed in your name.
- Dubai law requires off-plan payments to go into a project escrow account used only for construction.
- The Central Bank caps off-plan mortgages at 50% of the value, lower than the limits on ready homes.
- A ready home can be inspected and rented from day one; off-plan income starts only after handover.
What is the difference between off-plan and ready property in Dubai?
An off-plan property is bought from the developer before it is built or finished, under the developer’s own sale and purchase agreement (SPA). A ready property is a completed home, usually bought from its current owner on the secondary market under Form F, the standard resale contract set by the Real Estate Regulatory Agency (RERA). Both are registered with the Dubai Land Department (DLD), and both carry the same 4% DLD registration fee. What differs is when you pay, what you can check before you commit and when the home can earn rent or be lived in.
| Question | Off-plan | Ready (resale) |
|---|---|---|
| Who you buy from | The developer | Usually the current owner |
| Contract | Developer’s SPA | RERA Form F |
| How you pay | Instalments set by the developer’s payment plan | Deposit, then the balance at transfer |
| Registration | Interim register (Oqood), title deed after completion | Title deed issued at transfer |
| Where your money goes | Project escrow account | To the seller (and their bank) at transfer |
| Can you inspect it? | Plans, show units and project progress only | Yes, the exact home |
| Maximum mortgage | 50% of value | Up to 80% for an expatriate’s first home up to AED 5M; lower above that and for investment homes |
| Rental income | After handover | From transfer (or the existing lease) |
| Main risk | Delay, specification and completion risk | Condition, price and the seller’s position |
How do off-plan payment plans compare with paying for a ready home?
Off-plan homes are usually paid for in stages under a payment plan set by the developer: a booking amount, instalments during construction and a final payment at or after handover. The schedule, and whether any of it falls after handover, is a commercial term in the SPA, so compare plans line by line rather than by headline.
A ready home is paid for in two main steps. A deposit (commonly 10%) is paid when Form F is signed, and the balance is paid on transfer day, with the 4% DLD fee and the other costs in the transfer costs guide. That means more cash, or a larger mortgage, at once, but the home is yours from that day.
What is Oqood, and when do you get a title deed?
Oqood is DLD’s system for registering off-plan sales in its interim (provisional) register. Under Law No. 13 of 2008, a sale of an off-plan unit must be entered in that register, and a sale not entered is void. The developer registers the sale through DLD’s Oqood portal; once registered, the buyer’s interest can itself be sold or mortgaged under the law.
The title deed comes later. When the project is complete and the developer has finished its registration steps with DLD, the unit moves to the main property register and a title deed is issued. With a ready home, the title deed passes to you at the trustee office on transfer day.
How does escrow protect off-plan buyers in Dubai?
Law No. 8 of 2007 on escrow accounts for real estate development is the main protection for off-plan money. In summary:
- A developer must apply to DLD to open an escrow account before selling units off-plan.
- Payments from off-plan buyers, and from the project’s financiers, are deposited into an account opened in the project’s name with an approved escrow agent.
- The account is dedicated to building that project, and the developer’s creditors cannot attach the money in it.
- After the completion certificate, the escrow agent keeps 5% of the account for one year from registration of the units in the buyers’ names.
Escrow reduces the risk that your instalments are spent elsewhere. It does not remove the risk of delay, of a change in specification, or of a project that stalls. Pay only into the project escrow account named in your SPA, never to a personal or unrelated account.
How can you check an off-plan project before you buy?
- Find the project with DLD. DLD’s real estate project status service lets you search by project name, project number or plot number and see its completion status.
- Check it in Dubai REST. DLD’s Dubai REST app shows project information including the percentage of completion, project photographs and the escrow account number.
- Match the escrow details. Confirm that the escrow account in your SPA and payment instructions is the project’s registered account.
- Read the SPA. Look at the anticipated completion date, what happens if it slips, the specification, the service-charge basis and any conditions on reselling before handover.
- Confirm Oqood registration. Ask for the registration after you pay, and keep the reference.
For a specific SPA or a delayed project, take advice from a UAE-qualified lawyer.
What about handover delays, inspection and rental income?
Handover. Completion dates in an SPA are estimates with terms attached. A delay pushes back the date you can move in or let the home, and the date any post-handover payments begin. Plan your finances around a later date than the one in the brochure.
Inspection. With a ready home you can walk the exact unit, check its condition, its outlook and its building, and compare it with registered sales of similar homes. Off-plan, you are relying on plans, a show unit and the developer’s specification until handover, when you should inspect carefully before accepting the keys.
Rental income. A ready home can be let as soon as it transfers, or comes with an existing tenancy. An off-plan home earns nothing until it is handed over and let, while instalments may already be due.
Can you get a mortgage, or resell, before handover?
Mortgages. The Central Bank of the UAE caps the loan-to-value on any off-plan purchase at 50%, whatever the buyer’s category or the home’s value. For ready homes, the caps are higher: for an expatriate’s first home, 80% up to AED 5 million and 70% above, and 60% for second and investment homes. Non-residents usually face tighter, bank-specific terms. Many off-plan buyers therefore fund the construction stages from their own cash.
Reselling before handover. Once an off-plan sale is registered in the interim register, the law allows the buyer to sell their interest. In practice the developer’s NOC is needed, and developers set their own conditions, which may include how much of the price must be paid first and an administration fee. Check the SPA before relying on an early exit.
Which suits you: off-plan or ready?
Ready tends to suit buyers who need to move in or earn rent soon, buyers borrowing more than half the value, and anyone who wants to judge the exact home, the building and the community before committing. The secondary-market guide explains the resale process.
Off-plan tends to suit buyers with a longer horizon who can fund the instalments, value a staged payment plan or a new specification, and accept delay and completion risk.
Write down when you need the home to be usable and how you will fund every payment if handover slips by a year. If either answer is uncomfortable, a ready home is usually the safer comparison.
To compare specific options, start with a buying brief.
Frequently asked questions
Is off-plan property cheaper than ready property in Dubai?
Not necessarily. Off-plan prices are set by developers and spread over a payment plan, while ready prices are set by the resale market. Compare the total cost, the timing of payments and the income you give up while waiting.
Is my off-plan payment protected?
Off-plan payments must go into the project’s escrow account under Law No. 8 of 2007, and that money is dedicated to building the project. Escrow does not remove delay or completion risk.
What is the maximum mortgage on off-plan property?
The Central Bank of the UAE caps off-plan mortgages at 50% of the property value, regardless of the buyer or the price.
Do I pay the 4% DLD fee on off-plan?
DLD’s initial sale registration lists 4% of the value. The developer’s sale agreement sets who bears it, so check that clause.
Can I sell an off-plan unit before completion?
Often, once it is registered in the interim register, but the developer’s NOC and conditions apply, and these vary by developer and project.
Sources and limits
General information, not legal or financial advice. Laws are summarised, not reproduced; developer terms, bank lending and DLD procedures vary and change. Check your SPA or Form F with a UAE-qualified lawyer and confirm lending terms with your bank.
- Dubai Legislation Portal — Law No. (8) of 2007 Concerning Escrow Accounts for Real Estate Development
- Dubai Legislation Portal — Law No. (13) of 2008 Regulating the Interim Property Register
- Dubai Land Department — Request to Register the Initial Sale (Oqood)
- Dubai Land Department — Real estate project status
- Dubai Land Department — Dubai REST
- CBUAE Rulebook — Regulations Regarding Mortgage Loans, Article 3 (loan-to-value limits)
- CBUAE Rulebook — Resolution No. 31/2/2020 amending the mortgage regulations
Sources checked October 3, 2026.